Explore benefits for teams across locations, roles and varying schedules.
Traditional group plans are under pressure
Rising premiums and unpredictable renewals can make traditional group insurance harder to sustain. MRAChoice offers a different approach: you define the contribution, while employees compare individual health plans available where they live.
Compare your current benefits spend with a defined contribution model.
MRAChoice does not add a broker fee to this offering.
The proposed administration and premium payment model does not require you to hire a separate third-party administrator.
A clearer path to savings
With an individual coverage health reimbursement arrangement, or ICHRA, you set an employer contribution. Eligible employees use it toward qualifying individual health plans available in their residential area.
We compare your current spending with contribution scenarios and local plan prices. The analysis shows possible employer and employee savings alongside the networks, prescriptions and out-of-pocket costs that make a plan workable in real life.
Built for diverse teams
Whether your employees work across locations, shifts or job types, coverage options can be reviewed by each person’s residential area.
Review provider networks, specialty care and continuity for clinical and support staff.
Explore benefits for teams across locations, roles and varying schedules.
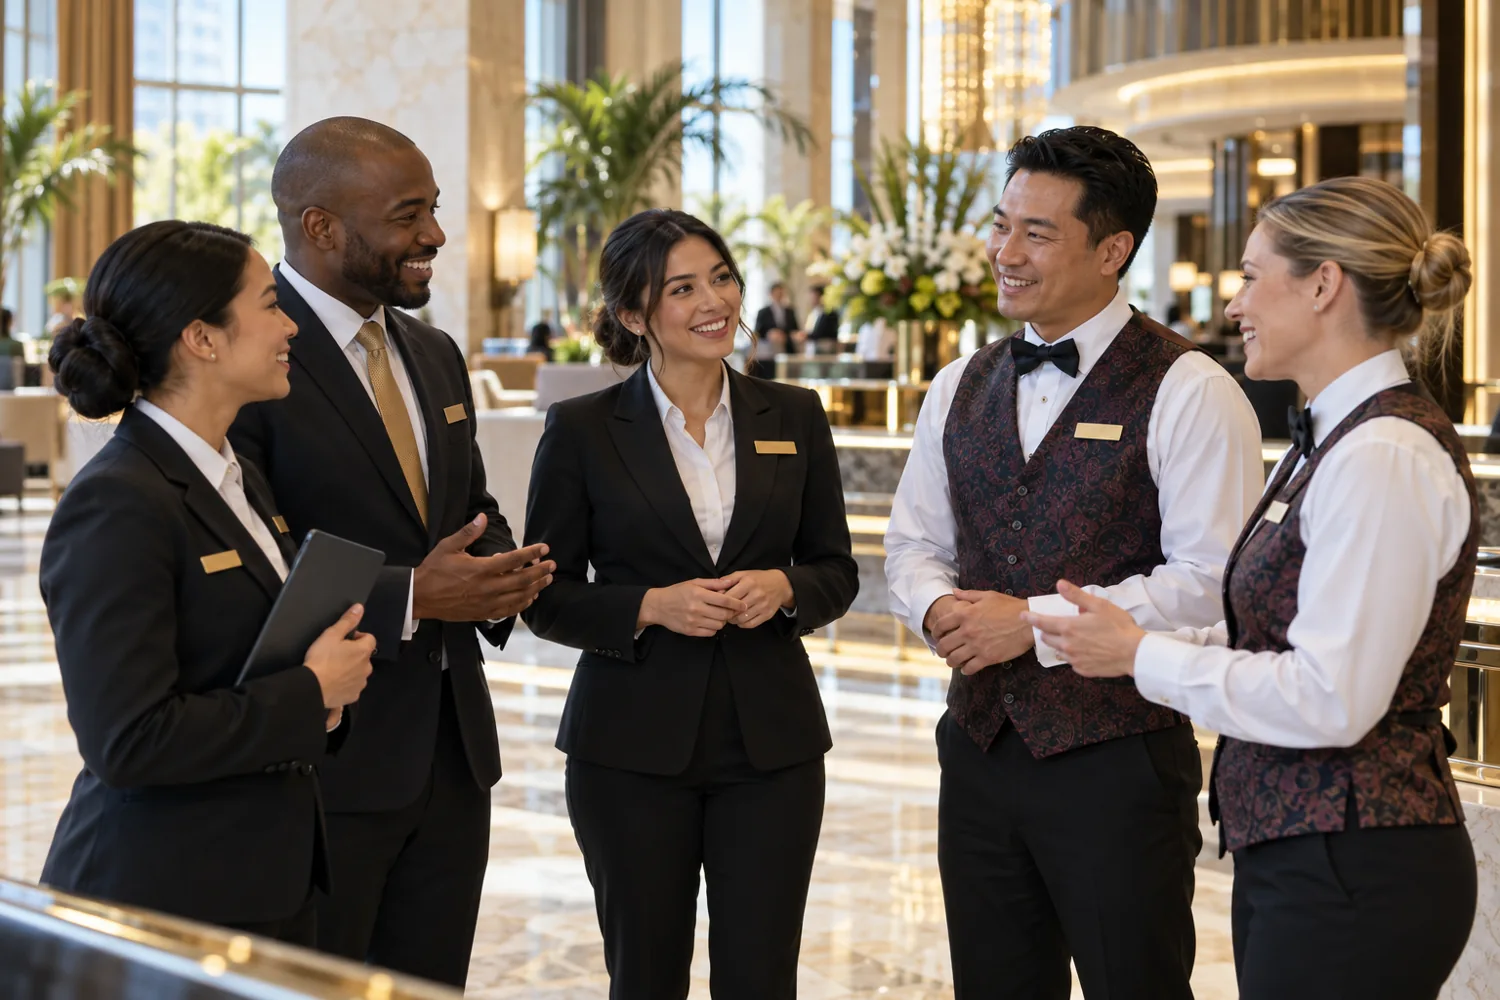
Offer employees options that reflect where they live and receive care.
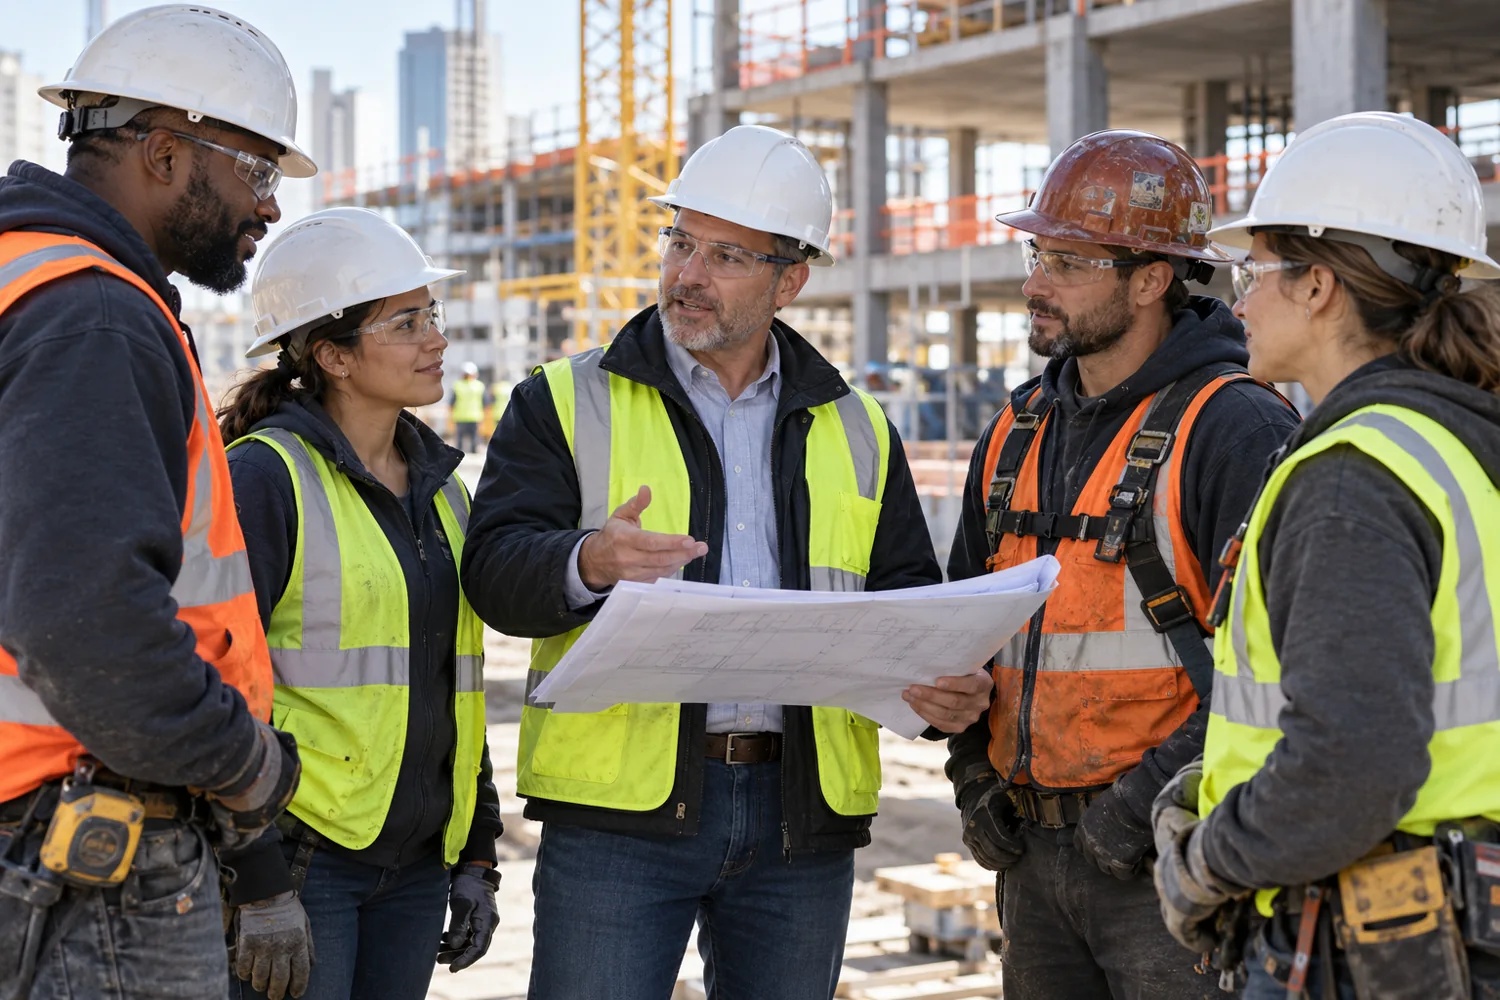
Compare local coverage for teams who work across sites and regions.
We model employer costs and employee premiums together. Savings only matter if the available plans meet the workforce’s needs.
Use a completed employee census, including eligibility, age, compensation and location, to build accurate scenarios.
See your current employer spending beside proposed allowances, projected annual costs and employee premium ranges.
Review available plans by ZIP code, including doctors, hospitals, prescriptions, deductibles and annual out-of-pocket limits.
Coordinate enrollment guidance, communication and payroll reporting so HR and employees know what to expect.
We model employer costs and employee premiums together. Savings only matter if the available plans meet the workforce’s needs.
Use a completed employee census, including eligibility, age, compensation and location, to build accurate scenarios.
See your current employer spending beside proposed allowances, projected annual costs and employee premium ranges.
Review available plans by ZIP code, including doctors, hospitals, prescriptions, deductibles and annual out-of-pocket limits.
Coordinate enrollment guidance, communication and payroll reporting so HR and employees know what to expect.
What changes for employers and employees
An ICHRA can give employers a defined contribution and employees access to individual plans. A successful transition also depends on careful review of each plan and clear employee education.
Set a contribution strategy in advance and model monthly and annual costs. Potential savings depend on your current plan, contribution design and local market.
Employees choose among plans available where they live. Depending on the policy, someone leaving the company may be able to keep the individual coverage by paying its premium.
Networks and drug coverage vary by carrier and plan. Employees should verify their preferred providers, prescriptions, service area and total potential costs before enrolling.
Common questions
These answers outline the questions we would test against your workforce and available plans.
That depends on the plan and service area. We compare available plan networks with the providers and facilities employees care about. Each employee should verify participation before enrolling.
We can model age-based contribution scenarios and show expected employee premium responsibility by age and location. Qualified advisors should review the final contribution design for ACA affordability and compliance.
Employees need to compare each plan’s formulary, specialty tier, prior authorization, coinsurance, deductible and annual out-of-pocket maximum. Coverage can differ materially between plans.
Our proposed payment process uses a consolidated employer payment with premium distribution and reconciliation. HR and Payroll use a contribution report to establish employee deductions. Payroll integrations are targeted for summer 2027.
The first year calls for more communication and education than a routine group-plan renewal. Employees take an active role in choosing coverage, so plan comparisons and support must be easy to understand.
A practical first step
A workforce-specific review compares your current employer spend with MRAChoice contribution scenarios, available plans and employee cost ranges. Ask your MRAChoice representative for a benefits strategy discussion.
Don't miss out on your potential savings!
Additional Information